Understand what members need, not just what they do: Hesta's GM Digital; why customer confidence matters more than clicks
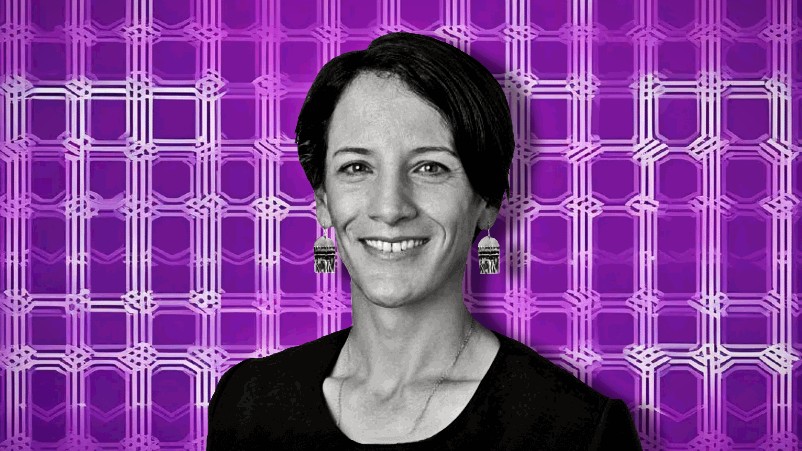
Hesta GM digital, Georgie Obst
Most organisations are good at recording what customers do. Far fewer understand why they do it. For HESTA GM Digital Georgie Obst, closing that gap means building around what members need, not just what the data shows. The million-member fund is combining member research and segmentation, AI-enabled experiences and member choice to do it. Early results include an 87 per cent final-slide completion rate among members who started its AI-enabled annual engagement experience, and a 10 per cent increase in satisfaction following a digital service overhaul.
What you need to know:
- Understanding, not just data: GM Digital Georgie Obst says organisations can measure customer behaviour with precision, but still need to ask to understand what customers need.
- Segmentation only gets you so far: the fund uses nine customer segments combining demographics, financial preparedness and psychographics. But Obst warns that even sophisticated targeting can misread customer motivations and circumstances.
- AI delivers early engagement gains: An AI-enabled, gamified end-of-financial-year experience has achieved an 87 per cent final-slide completion rate, while a separate digital non-lapsing binding nominations initiative has been followed by a reported 10 per cent lift in customer satisfaction.
- Customer experience trumps digital bells and whistles: Obst argues that traditionally marketers can focus too heavily on acquisition while neglecting existing customers. HESTA measures financial confidence and retirement readiness alongside conventional engagement metrics.
- Let customers choose: HESTA is introducing flexible retirement journeys that allow members to explore content, attend webinars or seek financial advice when they’re ready, rather than forcing everyone down the same path.
I love fashion, but my obsession this year is pre-loved designer. So, is that a value shopper or a luxury shopper? ... The data tells you what I’ve done. Those are all things I’ve done. It doesn’t tell you what I need.
Hesta's GM Digital Georgie Obst says companies can measure customer behaviour with considerable precision while still missing what customers actually need.
The million-member superannuation fund is combining psychographic segmentation, AI-enabled experiences and greater customer choice to improve members’ financial confidence and retirement readiness.
Speaking at the recent Martech Oktoberfest event in Melbourne hosted by RMIT and Helium, Obst said customer behaviour can be measured precisely while the motivations behind it remain elusive, and she described her own behaviour as a consumer to make the point.
She illustrated the limitations with her own consumer profile. Her occupation might make her a logical target for marketing technology webinars, while her interests in swimming, fashion and shopping could place her in several other audiences. Each classification would be accurate without necessarily revealing what she wanted at a particular moment.
“I love fashion, but my obsession this year is pre-loved designer. So, is that a value shopper or a luxury shopper? ... The data tells you what I’ve done. Those are all things I’ve done. It doesn’t tell you what I need,” Obst said.
Knowing versus understanding
Hesta serve more than one million Australians, predominantly working in health and community services, and uses nine member segments incorporating demographic information, projected retirement preparedness and psychographic characteristics.
One customer segment, labelled “frozen by fear”, comprises members over 45 who are financially unprepared for retirement and anxious about their future. Another, “performing with potential”, comprises younger members managing their money well who expect comprehensive digital services.
“They expect to engage with us online and be able to do everything online. They do not want to call us,” Obst said of the younger group.
The segmentation helps the business determine messaging, tone and engagement approaches, supported by data science and propensity modelling. But Obst cautioned against assuming even sophisticated segmentation provides a complete picture of individual circumstances.
“These groups give us a good start. They’re a useful lens. They help us with messaging and tone, and where a member probably is on the path to retirement. It’s a starting point. Definitely not a destination.”
From acquisition to customer care
Obst also questioned the tendency to concentrate personalisation efforts on customer acquisition while leaving established relationships to different teams and systems. She described abandoning an online Nike purchase after being asked to create a profile, despite already having an account established in-store. By contrast, an SMS reminder from her insurer led to a straightforward renewal through its app, where she could adjust her excess and complete the transaction.
The comparison illustrated how friction can undermine purchase intent, while convenient service can strengthen an existing relationship.
For Hesta, whose members may remain with the fund for more than two decades, the distinction has particular significance.
“What we’re trying to build is confidence, and that’s what we measure as well. We measure confidence in our members. We measure retirement readiness,” Obst said. “Looking after someone is harder than it sounds. As I say, it doesn’t show up in a click rate. It’s a feeling; you can’t see it from the data.”
By way of an example, she said, “We introduced a product update in July this year: non-lapsing binding nominations. My team had the job of digitising that experience. That’s how layers help: The product change was there; we could make it easy. We’re seeing thousands sign up every couple of days, and it’s going well – members are taking it up which is fantastic.
“But what a member remembers is, hopefully, that it was easy. They didn’t have to call. They didn’t get stuck. But the reassurance: ‘Oh, you’ve helped secure my family’s future.’”
Obst said customer satisfaction had increased 10 per cent since the change, alongside improvements in ease-of-use scores. She did not specify the baseline or whether the satisfaction increase represented percentage points.
Hesta has also introduced an AI-enabled, gamified end-of-financial-year experience that guides members through various interactive screens presenting information about their superannuation.
Obst said 87 per cent of users were reaching the final screen, which encourages members to nominate a beneficiary. The initiative was relatively new, and she did not disclose participation numbers or resulting nomination rates.
Recognition, trust and the role of brand
Despite extensive customer records across the superannuation industry, Obst cited Forrester research indicating only 39 per cent of customers believed their fund knew their account history well. Forrester had identified legacy systems and integration challenges as contributors to the difficulty of demonstrating customer understanding.
Brand also plays a significant role in this approach. With more than 80 per cent female membership, the fund seeks to reflect the circumstances of health and community services workers rather than conventional retirement advertising featuring affluent couples strolling along beaches.
“They need to feel talked to, not talk down to, and we work really hard to try and represent them in everything we do,” Obst said.
That approach extends to digital financial planning tools and advocacy on issues affecting members, including superannuation payments on government-funded paid parental leave.
Hesta is now applying this thinking to retirement experiences that allow members greater control over how and when they engage. A feature in its app becomes available when members turn 60, offering retirement information, webinars and the opportunity to book financial advice. Members can also postpone engagement until they feel ready.
The approach recognises that people approaching retirement have different financial circumstances, expectations and appetites for advice, even when their demographic profiles appear similar.
Obst urged marketers to test their assumptions rather than treat behavioural data as definitive evidence of customer intent.
“The lesson I’ve learned time and time again: don’t assume anything. You can use data to tell whatever story you want, but do make great hypotheses. There’s a lot there that will inform you.”
Her closing recommendation was to give customers greater freedom to determine their own journeys. “Let the customer choose their own adventure. Optional pathways – this is how we’re thinking about retirement. Because I bet if I asked every single one of you in this room, you would all have different answers to what you wanted to do with your super and what you wanted to do in retirement,” she said.
“Give them options to write their own story.”